Nordex secured 2,810 MW of orders in its Projects segment in the third quarter of 2026, an increase of 29.5 per cent compared with the same period last year (Q3 2025: 2,170 MW). The orders came from 10 countries and covered various turbine variants.
Their total value was €2.5 billion (Q3 2025: €2.0 billion). The average selling price (ASP) remained broadly stable at €0.90 million per MW (Q3 2025: €0.93 million per MW). Sales totalled €2.2 billion in Q3 2026, an increase of 28.2 per cent year on year (Q3 2025: €1.7 billion). Earnings before interest, taxes, depreciation and amortisation (EBITDA) more than doubled to €278.2 million (Q3 2025: €135.9 million). The EBITDA margin improved to 12.7 per cent, compared with 8.0 per cent in the same quarter last year. Net income almost tripled to €147.1 million, compared with €51.7 million in Q3 2025.
As at 30 September 2026, the order book stood at €19.3 billion, up from €14.9 billion a year earlier. This comprised €12.2 billion in the Projects segment (30 September 2025: €9.3 billion) and €7.1 billion in the Service segment (30 September 2025: €5.6 billion).
Turbine production reached 2,363 MW in Q3 2026, a decrease of 7.0 per cent compared with the previous year (Q3 2025: 2,541 MW), in line with project schedules. Blade production increased by 16.8 per cent to 1,311 units (Q3 2025: 1,122 units). Of these, 337 were produced in-house (Q3 2025: 366), while 974 were externally sourced (Q3 2025: 756).
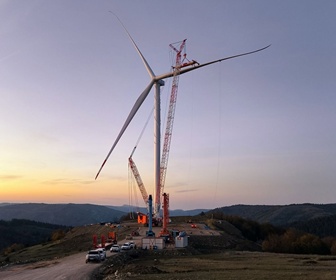
The company installed 331 wind turbines across 15 countries, representing a total capacity of 2,021 MW. In Q3 2025, the company installed 420 turbines across 16 countries, with a combined capacity of 2,576 MW. The lower installation volume was mainly due to customer delays, delays in obtaining transport permits and blade-related postponements in Türkiye. Europe accounted for 79 per cent of installed capacity, with North America representing the remaining 21 per cent.
Sales in the Projects segment reached €2.0 billion, an increase of 29.9 per cent year on year (Q3 2025: €1.5 billion). Service segment sales rose by 8.1 per cent to €237.0 million (Q3 2025: €219.2 million). The Service segment's EBIT margin was 20.6 per cent, exceeding the company's 20 per cent target. The Projects segment's EBIT margin improved by 2.0 percentage points to 13.1 per cent.
The company now expects a full-year 2026 EBITDA margin of 11.5 to 12.5 per cent, compared with its previous guidance of 8.0 to 11.0 per cent and sales for the full year between €8.2–9.0 billion.